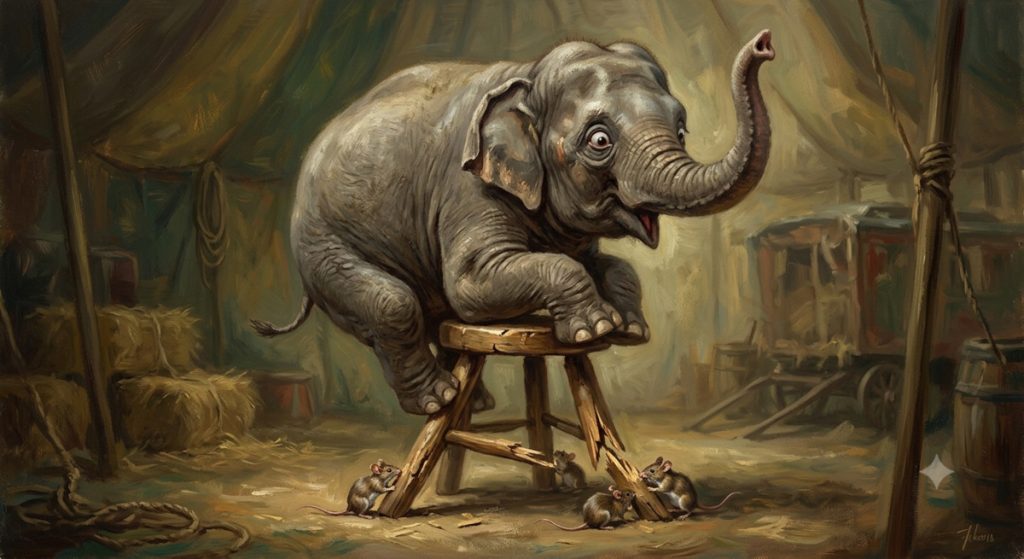
The stool has four legs. Three are already broken.


On the morning of July 31, 2026, Treasury Secretary Scott Bessent sat at a Camp David cabinet meeting with a notepad visible to Reuters photographers. It read: “To Do — Buy Japanese Yen (JPY) $5-10 bil.”
The Treasury acted within hours. The New York Fed executed the trade through Goldman Sachs and Morgan Stanley — selling euros, not dollars, to buy yen. First joint US-Japan currency intervention in fifteen years. Coordinated. Deliberate. Funded from the wrong pocket to avoid weakening the currency it was designed to protect.
The yen spiked. Then, over the following days, it gave most of it back.
This is what it looks like when the circus is past its prime. The elephant is still performing. The stool is still holding. But three of its four legs are cracked through, and the mice have been gnawing at the base for years.
The Stool
The United States national debt crossed $39 trillion on March 17, 2026. The standard reassurance — that 76% is held domestically — conceals two accounting fictions.
The first: $7.6 trillion is intragovernmental debt, the government’s IOU to its own Social Security and Medicare trust funds. The government borrowed from itself and issued itself a receipt. The second: the Federal Reserve holds $4.4 trillion in Treasuries purchased during successive rounds of quantitative easing — purchased, that is, by creating reserves from nothing and crediting the Treasury’s account. The largest single holder of American debt acquired it by printing the money to buy it.
Strip those two fictions from the domestic total and the genuine outside creditors are approximately $14 trillion in domestic private investors and $9.3 trillion in foreign holders. Of the foreign $9.3 trillion, three pillars have supported the structure for decades. Each is now cracking under its own weight.
Leg One: Japan
Japan holds $1.2 trillion in US Treasury securities. It became the largest foreign holder in 2019 when it overtook China. The arrangement that produced this holding was not an investment decision. It was a structural subordination.
For thirty years, the Bank of Japan held interest rates at zero or below zero. Japanese savers earned nothing on deposits. Zombie corporations survived on cheap credit that productive capital allocation would have denied them. Domestic investment was starved in favor of carry trade mechanics: borrow yen at 0%, buy US Treasuries at 4-5%, pocket the spread. The carry trade generated structural demand for dollar assets that kept US borrowing costs artificially suppressed. Japan’s economy was the collateral damage.
The accumulated wreckage is a debt-to-GDP ratio exceeding 250%. The trap this created is total: raise rates to defend the yen and the carry trade unwinds, flooding the Treasury market with selling; hold rates at zero and the yen collapses, triggering the same unwind by a different mechanism. The BOJ has been choosing between two versions of the same catastrophe for a decade.
In 2024, a modest rate increase triggered a partial carry trade unwind that briefly crashed global equity markets before coordinated intervention contained it. The July 2026 intervention — Camp David, Goldman and Morgan Stanley, euros not dollars — is the same story, larger. The yen recovered briefly and then erased most of the gain. The market has now price-discovered the limits of the firepower.
This leg is cracking from the inside out. It has been since 1990.
Leg Two: China
China held $1.32 trillion in US Treasuries at its peak in 2013. It now holds approximately $700 billion. That is a 47% reduction over thirteen years — deliberate, sustained, and accelerating with each escalation of the trade war.
China was the largest foreign holder of US debt from 2009 through 2018. The mechanism was the same as Japan’s in broad outline: trade surpluses with the United States generated dollars, which were recycled into Treasuries as the price of maintaining the export-led growth model under dollar hegemony. The difference is that China, unlike Japan, retained enough strategic autonomy to begin unwinding the arrangement on its own terms.
The unwinding has been patient and consistent. No dramatic dump, no announced policy — just steady reduction, year after year, while simultaneously building alternative reserve assets in gold, bilateral currency swap arrangements, and BRICS payment infrastructure. Beijing has been watching the structural fragility that most Western analysts still deny and positioning accordingly.
The third-largest foreign holder of US debt is in deliberate exit. The trade war has converted a slow exit into an accelerating one. The export revenues that once recycled into Treasuries are now recycling elsewhere.
This leg was sawn halfway through before most people noticed it was being touched.
Leg Three: The Gulf States
The petrodollar arrangement is older than most of its beneficiaries understand. In 1974, three years after Nixon closed the gold window and destroyed the Bretton Woods system, Henry Kissinger negotiated a replacement architecture with Saudi Arabia: oil would be priced exclusively in dollars, and petrodollar revenues would be recycled into US Treasury securities and weapons purchases. In exchange, the United States provided military protection for the Saudi monarchy.
It was tribute dressed as investment. The Gulf states earned dollars from oil sales, held dollars in reserves because oil was priced in dollars, and parked those reserves in Treasuries because Treasuries were the most liquid dollar-denominated asset. Every barrel of oil sold anywhere in the world generated structural demand for dollars and, downstream, for US government debt.
The Strait of Hormuz closure disrupted this mechanism at its source. When 750 ships are trapped in the Gulf, when Qatar declares LNG force majeure, when Iraqi production drops 70% and oil prices spike toward $94 a barrel, the petrodollar recycling slows. Gulf sovereign wealth funds facing domestic fiscal pressure and a disrupted export picture are not steady buyers of thirty-year Treasuries. They are reviewing their options.
The Kissinger architecture is fifty-two years old. It was designed for a world of cheap energy, subservient allies, and unchallenged American military reach. None of those conditions currently obtain.
In the past week since this article was first drafted, the fracture has deepened significantly. Saudi Arabia had been managing the Hormuz closure by routing oil through the East-West Pipeline across the Arabian Peninsula and exporting through the Red Sea port of Yanbu — a bypass that kept the petrodollar mechanism partially functional while Hormuz was blocked. On July 22, 2026, the Houthis closed that exit too. After a nine-month pause, Houthi militants resumed attacks on vessels in the Red Sea, directly targeting Saudi Arabia and announcing a maritime embargo of Saudi ships near the Bab el-Mandeb Strait. Eight ships have been targeted with four sustaining damage. The other four Saudi tankers were forced to turn around. Ship traffic through Bab el-Mandeb dropped to its lowest level in months.
Saudi Arabia is now encircled. Hormuz blocked to the east. Bab el-Mandeb blocked to the west. The bypass route that kept exports moving is itself under attack, along with Abqaiq — the crucial processing facility that acts as the nerve center for Saudi oil, which has come under attack from both the Houthis and Iranian-aligned groups in Iraq.
The geopolitical signal is equally significant. Turkey, Saudi Arabia, and Pakistan are reported to be forming the first Islamic military alliance which demonstrates they will no longer depend on US security guarantees, and Bin Salman has reportedly said as much. The statement has been largely suppressed in Western media, but its implications for the petrodollar architecture, which was always a security arrangement disguised as a financial one, are profound.
This leg is no longer merely cracked. It is being actively broken from both ends simultaneously.
Leg Four: The Fed
The Federal Reserve is not, in the honest sense, a buyer. It is a printer. Its $4.4 trillion in Treasury holdings were acquired by creating electronic reserves and crediting the Treasury’s account — a functional definition of debt monetization, dressed in the technical language of open market operations and quantitative easing. The largest single holder of American debt is the institution with the legal authority to manufacture the currency in which that debt is denominated.
The official narrative describes the Fed reducing its balance sheet from $6 trillion to $4.4 trillion through quantitative tightening. What the official narrative omits: the Bank Term Funding Program injecting backdoor liquidity after SVB’s collapse, the $2.5 trillion Overnight Reverse Repo drainage returning liquidity to the banking system as the balance sheet shrank, the Treasury General Account drawdowns injecting offsetting stimulus, and the creative distinction between actively selling securities and merely allowing them to mature. The net tightening delivered to the financial system is considerably less than the $1.6 trillion headline reduction implies. The buyer of last resort has been nominally stepping back while simultaneously deploying replacement liquidity through channels that don’t appear on the front page of the balance sheet. The fourth leg is not quite as solid as the official account suggests — nor quite as hollow as the balance sheet reduction implies. It is wedged in place by instruments that were not supposed to be permanent and cannot be maintained indefinitely.
At a weighted average interest rate of 3.36% on approximately $31 trillion in marketable debt, the United States currently pays $1.04 trillion per year in interest alone. That is $2.74 billion per day. It is now the third-largest line item in the federal budget, behind only Social Security and Medicare, and ahead of defense. Every basis point increase in the weighted average rate adds roughly $3 billion per year to that bill. Every year of additional deficit spending adds to the principal on which that rate applies.
The Fed cannot meaningfully cut rates without reigniting the 3.7% inflation that its own June PCE data documented. It cannot meaningfully raise rates without accelerating the interest cost spiral. It has held rates at 3.50-3.75% while three dissenting members voted for increases at the July 2026 meeting. The fourth leg is wedged into a notch and cannot move without starting the fall.
What Happens When the Stool Collapses
The sequence is not complicated. It is simply not discussed.
As the three foreign pillars reduce their Treasury holdings — Japan forced by the carry trade unwind, China by strategic deliberation, Gulf states by petrodollar disruption — the selling pressure falls on domestic private investors: mutual funds, pension funds, 401k accounts, insurance companies. To attract those buyers in the face of increasing supply, yields must rise. As yields rise, the $1.04 trillion annual interest bill grows. As the interest bill grows, the deficit widens further even without new spending. As the deficit widens, Treasury issuance increases. As issuance increases, yields must rise further to clear the market.
At some point in this progression, a large Japanese institution — a pension fund, a bank, a life insurer — faces a margin call large enough to require liquidating a significant block of US Treasuries. When that block hits the market, yields spike abruptly. The Federal Reserve, committed to its inflation mandate, faces an impossible choice: let yields spike and crash the housing market, the stock market, and the federal budget simultaneously, or step in as buyer of last resort and monetize the debt openly, ending the pretense that the dollar’s reserve status rests on anything other than the willingness to print.
Either path ends the performance. The first ends it through market discipline. The second ends it through currency debasement. The distinction matters less than it appears, because the debasement path merely converts a bond market crisis into an inflation crisis, and an inflation crisis into a political crisis, on a slightly longer timeline.
The elephant on the stool is not going to fall because it made a mistake. It is going to fall because the stool was always too small, always too fragile, always dependent on arrangements that required the subordination of allied economies to the maintenance of American privilege.
Japan sacrificed thirty years of domestic economic health. The Gulf states priced their sovereign resource in someone else’s currency. China funded the consumption of the nation it now competes with for global primacy. All three made the calculation that the arrangement was worth sustaining. All three are now making a different calculation.
The mice are not saboteurs. They are price signals.
The Camp David Note
Bessent’s notepad was either the most expensive accidental photograph in currency market history or the most deliberate non-announcement ever staged. Either way, it tells you where the Treasury’s head is.
They are not managing routine turbulence. They do not convene at Camp David and fund currency interventions with euros instead of dollars for routine turbulence. They do it when the system is close enough to cascading failure that the normal instruments are insufficient and the abnormal ones must be deployed with enough deniability to avoid triggering the panic they are trying to prevent.
The yen recovered briefly and gave most of it back. The carry trade is still unwinding. The interest bill is still compounding. China is still reducing its holdings. The petrodollar recycling is still disrupted.
The show, as they say, must go on.
It cannot go on much longer.
Sources
- Reuters. “Bessent’s to-do list: buy $5-10 billion worth of Japanese yen.” July 31, 2026. https://www.reuters.com/world/asia-pacific/bessents-to-do-list-buy-5-10-billion-worth-japanese-yen-reuters-photo-shows-2026-07-31/
- Financial Times. “US intervenes in currency markets to support Japanese yen.” July 31, 2026. https://www.ft.com/content/f6d563ee-9238-4f82-a848-79f2478326bd
- Bloomberg. “US Uses Euros to Buy Yen to Avoid Weaker Dollar, Strategists Say.” August 3, 2026. https://www.bloomberg.com/news/articles/2026-08-03/us-uses-euros-to-buy-yen-to-avoid-weaker-dollar-strategists-say
- Committee for a Responsible Federal Budget. “Q&A: Gross Debt Versus Debt Held by the Public.” March 19, 2026. https://www.crfb.org/papers/qa-gross-debt-versus-debt-held-public
- PrimeRates. “Who Owns the US National Debt?” May 2026. https://primerates.com/us-debt/who-owns-us-debt/
- Visual Capitalist. “Who Owns the $39 Trillion US Debt in 2026.” April 13, 2026. https://www.visualcapitalist.com/see-who-owns-the-39-trillion-u-s-debt-in-2026-from-domestic-and-foreign-holders-to-the-fed-and-mutual-and-pension-funds/
- USAFacts. “How much US government debt is owned by other countries?” March 2026. https://usafacts.org/answers/how-much-us-government-debt-is-owned-by-other-countries/
- Eichengreen, Barry. Exorbitant Privilege: The Rise and Fall of the Dollar and the Future of the International Monetary System. Oxford University Press, 2011.
- ZeroHedge. “US Treasury Informed Banks It May Intervene In Japan’s Yen.” July 31, 2026. https://www.zerohedge.com/markets/us-treasury-informed-banks-it-may-intervene-japans-yen-market-laughs-bojs-own-attempts-prop
- CME Group. Japanese Yen Futures Daily Volume. July 30-31, 2026. https://www.cmegroup.com/markets/fx/g10/japanese-yen.html
The author is an independent researcher and writer based in Dallas. This article is part of the Austrian Economics series.
Leave a Reply